How to Cut Your Monthly Payments with Interest Rates as Low as 4.5%
on June 20, 2025 at 04:00 AM
How to Cut Your Monthly Payments with Interest Rates as Low as 4.5%
With a second child on the way this summer, Kelley and Pete Di Martino needed more space. But moving from an apartment into a home proved to be easier said than done. In a seller’s market with limited inventory, they found themselves repeatedly caught in bidding wars that pushed the sale prices of existing homes beyond their budget.
Then they came across an opportunity to save about $400 per month on their mortgage by buying a new build from Allen Edwin Homes. Using a financing option called a 2-1 Buydown, the Di Martinos were able to get into a Move-In Ready home with an affordable monthly payment before their baby arrives.
“We were on a time crunch knowing we have the baby coming in July,” Kelley said. “We weren’t going to have time to build our own home, so we started looking at the Move-In Ready home option.
“The 2-1 Buydown just gives us that flexibility of having it be even more affordable and a little more peace of mind knowing that we’ll be in a comfortable spot.”
How the 2-1 Buydown Works to Save You Money
It’s not uncommon for homebuyers to pay “points” to lower the interest rate on their mortgage. Under the current Allen Edwin promotion, it’s the builder and the lender who cover the upfront cost of decreasing the mortgage rate by 2% for the first 12 months and then by 1% for the second year.
As a result, when you buy an eligible Move-In Ready Home from Allen Edwin with a mortgage rate of, say, 6.5%*, you’ll actually only pay 4.5% interest your first year and 5.5% your second year. Depending on the amount of the loan, the buydown saves a couple hundred to several hundred dollars per month on your mortgage payment.
The total cost to fund the two years of reduced rates comes out to about 2.3% of the total loan amount, said Derek Neher, executive vice president of Great Lakes Mortgage in Sterling Heights. On a $300,000 loan, that works out to about $7,000.
“The builder and I pay that,” Neher said. “It’s essentially a comfort loan. A lot of people can afford the house, but they’re not used to the bigger payment so they’re gun-shy. This program starts them out at the lower rate, which is a few hundred dollars a month less on the payment.”
The 2-1 Buydown can be especially helpful for homebuyers like the Di Martinos, who figure to have some extra expenses this summer as they welcome a new baby into the family. It’s also a nice way to reduce monthly payments in the short term for homebuyers who may have just a year or two left on a car loan, for example, or who are finishing school and will be starting a job with higher income in the next couple years.
Whatever your personal situation, you can benefit from a 2-1 Buydown when buying a Move-In Ready home from Allen Edwin. You can even choose to have the money buy down your rate for the full term of a 30-year fixed mortgage, if you prefer, or have it go toward your closing costs.
“We have an exclusive program to work with buyers when they buy a quick delivery showcase home,” Neher said. “This will save them thousands of dollars in the beginning years of their new mortgage and give them a new home at an affordable payment.”
‘We Just Feel Blessed’
When they first started looking to buy a home, the Di Martinos got discouraged. As soon as they saw a house go up for sale, it seemed that there already were offers from other buyers that went above and beyond the asking price. They wondered if their growing family might be stuck paying rent on their Kalamazoo residence.
Fortunately, they changed course and began looking at Move-In Ready homes by Allen Edwin.
“You start getting into bidding wars with these existing homes,” Pete Di Martino said. “Even if you put an offer in for the price that they’re asking, someone comes in and outbids you. That’s disappointing.
“With a new build, you’re not fighting anybody. You sign the contract, you put your earnest money down and then, boom, you’ve got your home."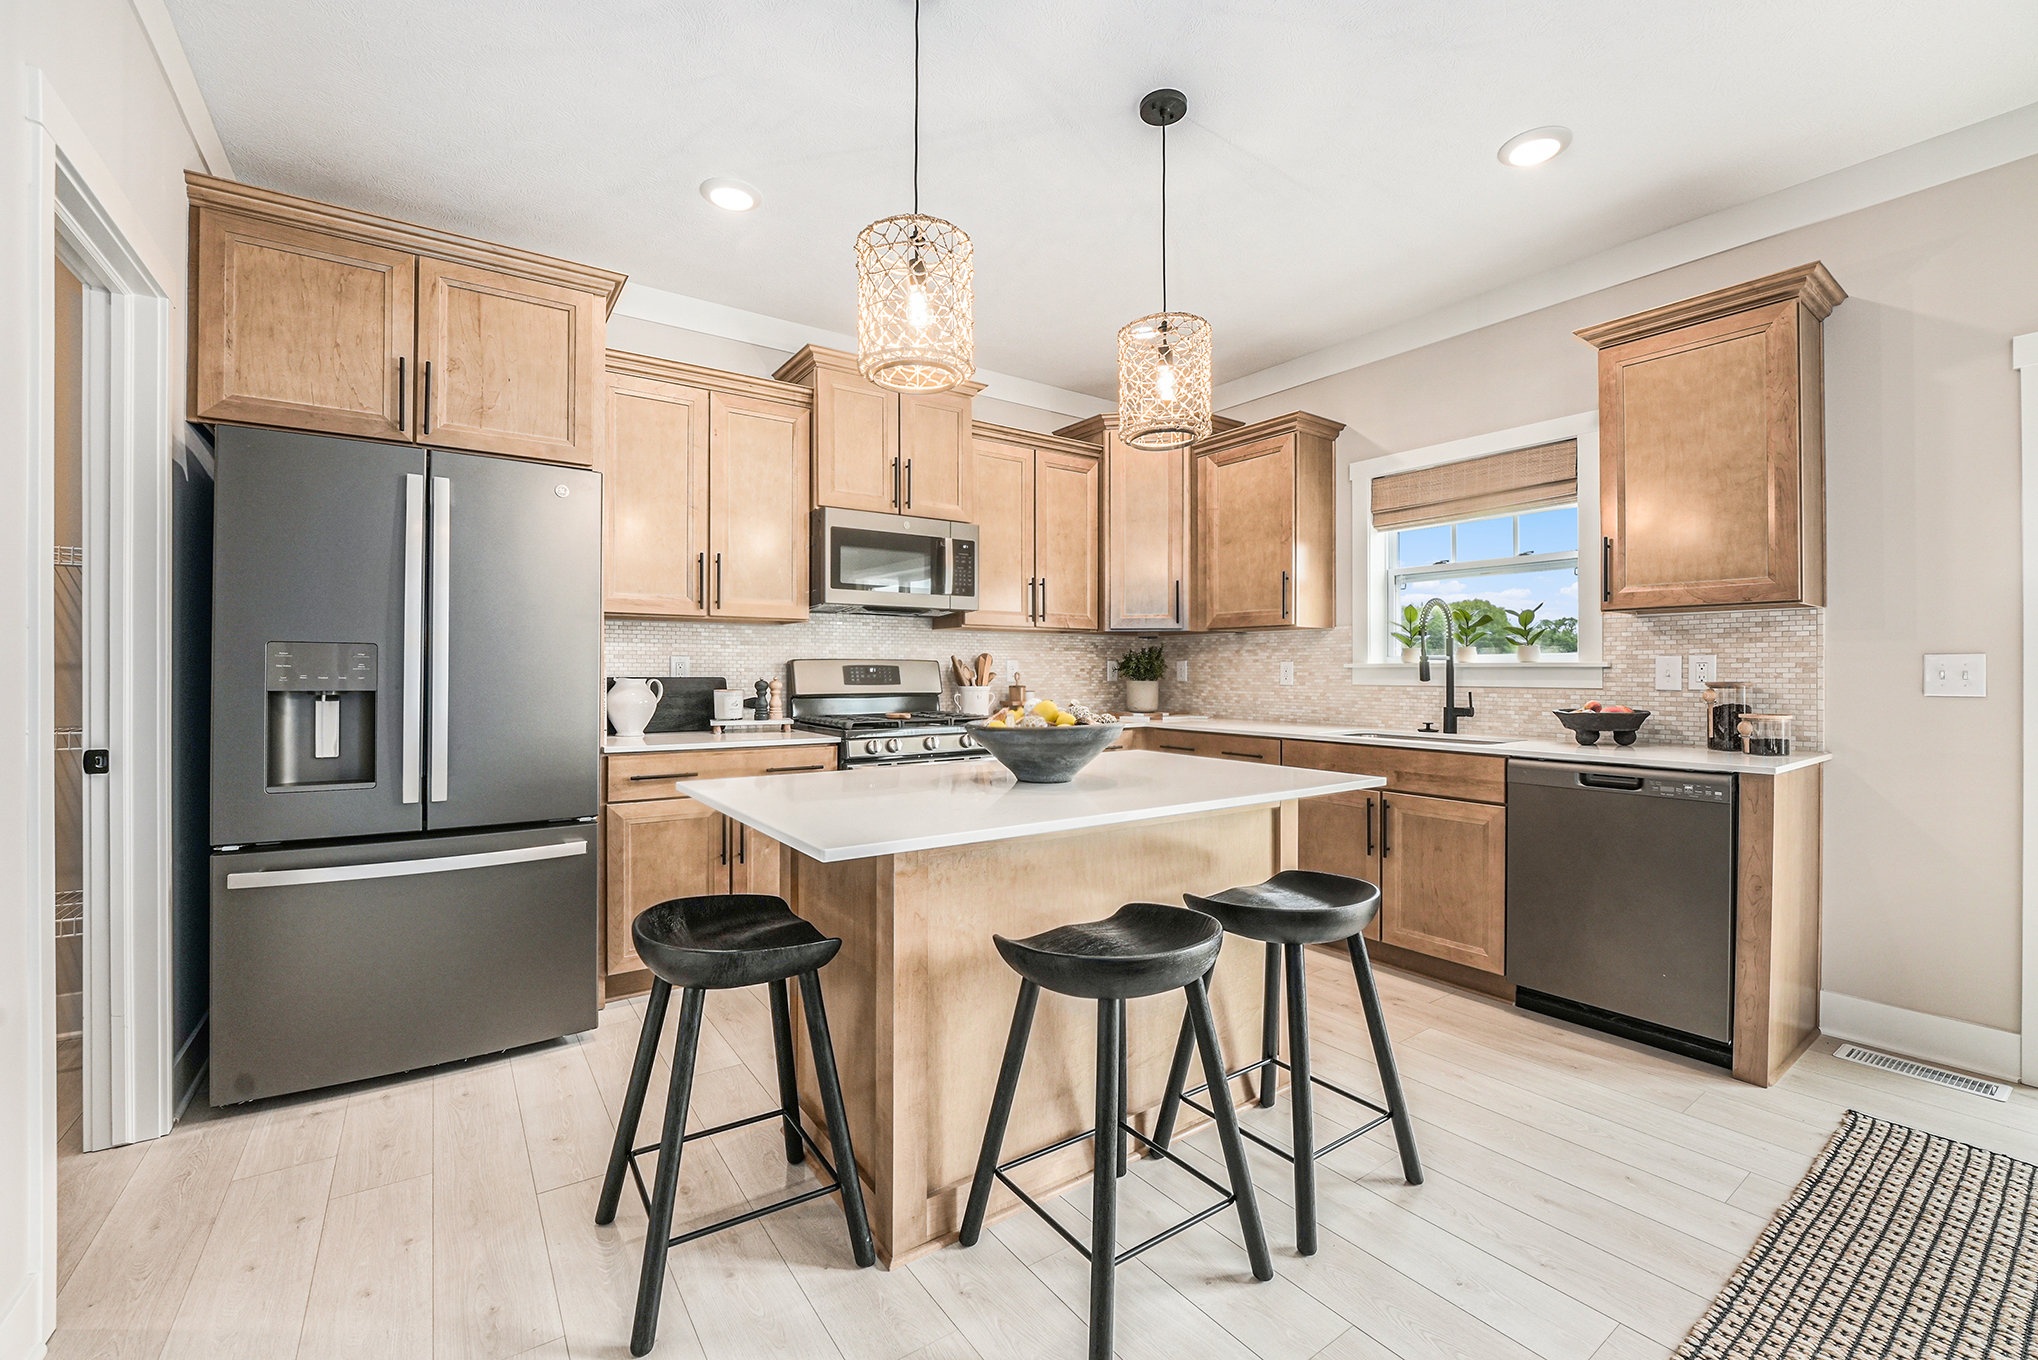
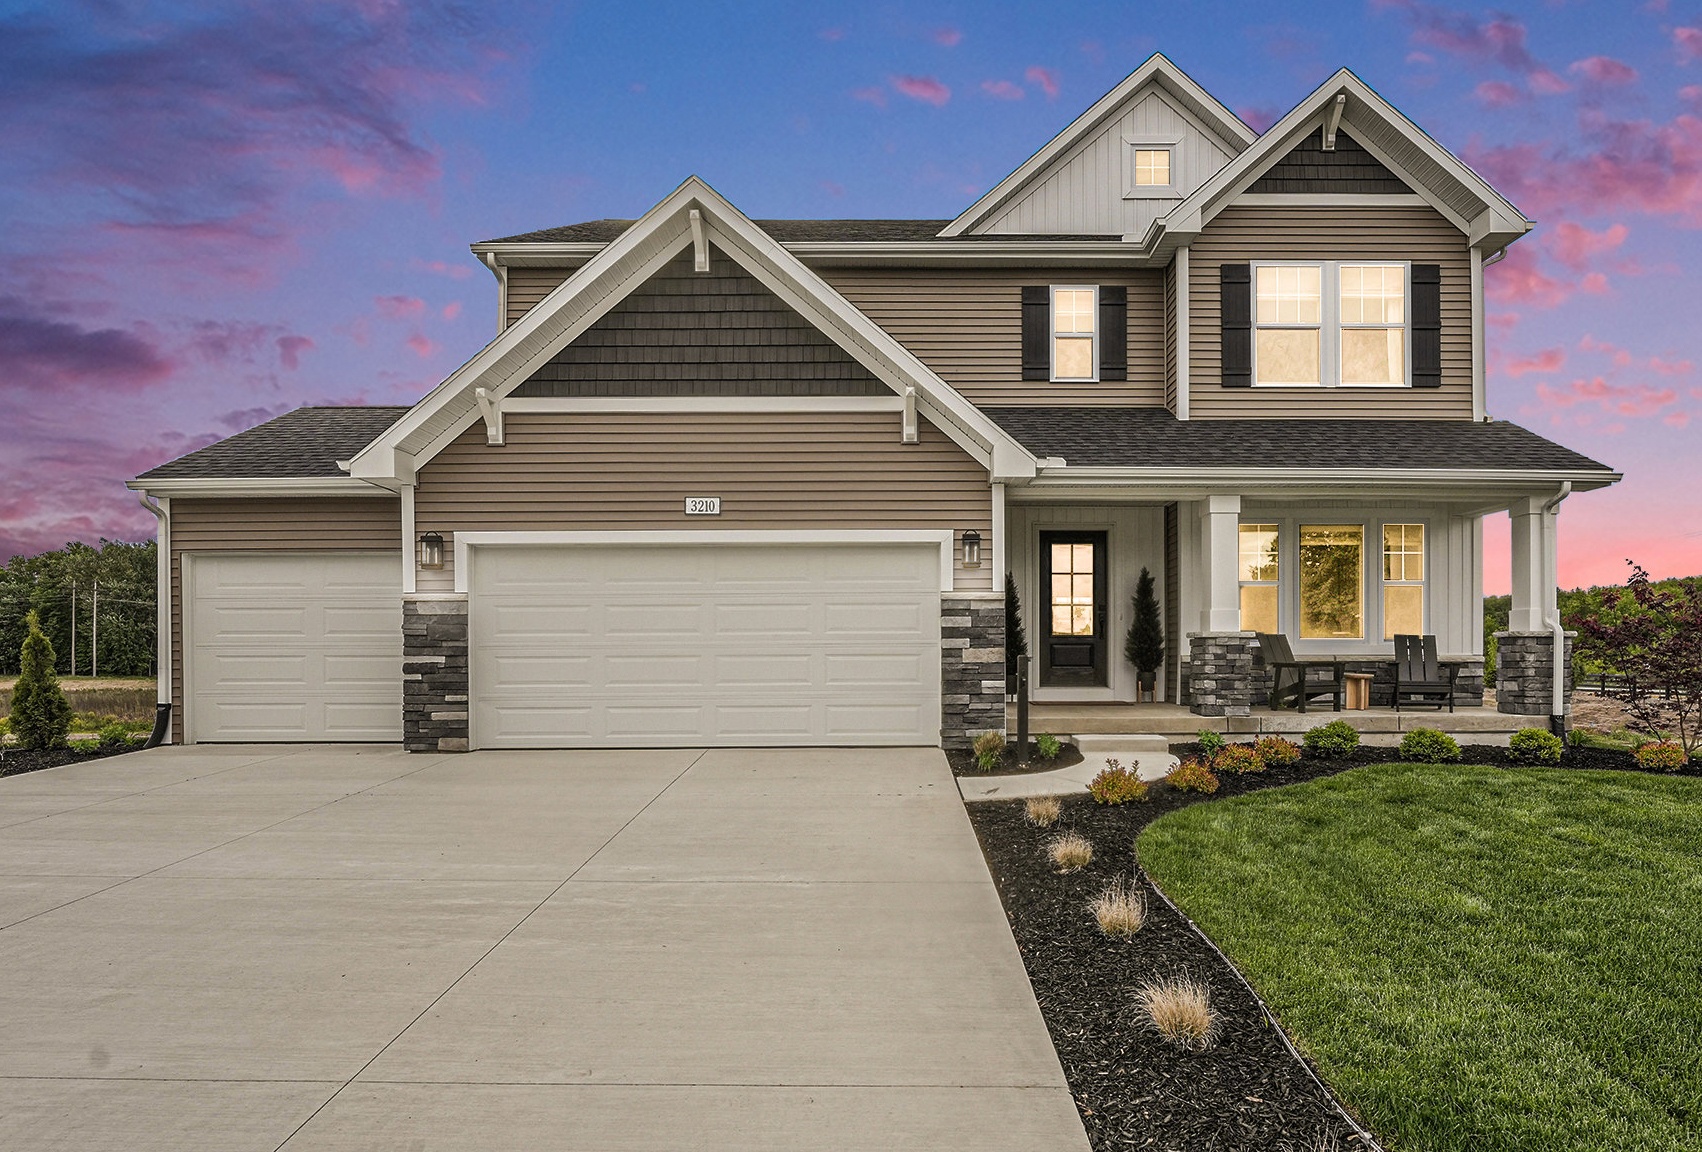
The place the Di Martinos now call home is a two-story Integrity 2080 floorplan in Allen Edwin’s Silver Oaks community in Mattawan, near Kalamazoo. The home features an open layout that’s great for entertaining, a small office that’s perfect for remote work and enough upstairs bedrooms for the kids and guests, too. There are sliders out to a back patio that overlooks a giant yard on their almost one-acre lot, and a basement they plan to finish as their kids get older.
Plus, they have friends who live just down the street and there are lots of other families in the neighborhood, too.
“It just checked all the boxes of what we were looking for,” Kelley said. “At the end of the day it’s a great investment. You don’t want to be throwing your money away renting forever.”
On top of future equity in their new home, the Di Martinos are getting around a $7,000 head start through Allen Edwin’s 2-1 Buydown financing program. Even if rates go down in the next couple years and they refinance their loan, they’ll still get any money that may be left over from the buydown.
“For us there really was no risk in doing this because it was not any of our own money,” Kelley said. “We just feel blessed that we had this opportunity presented to us and that we were able to find something that really did fit our needs and our financial situation.”
*Great Lakes Mortgage, DBA Mortgage 1 Inc. NMLS# 129386, is not affiliated with your current lender. This is not a commitment to lend. Restrictions apply. All Rights Reserved. Mortgage 1 Inc. is not acting on behalf of or at the direction of federal government. The actual payment amount will vary based upon credit history, rates in effect at the time of consummation, LTV and other credit factors. An LTV ratio above 80% may result in a need for mortgage insurance. If mortgage insurance is required, the amount of your payment will increase. The APR is subject to change at any time prior to consummation, and individual APRs may vary for loan purchases and loan refinances due to loan programs being offered, loan volume, or other factors. All borrowers are subject to qualification, underwriting approval, lender terms, and conditions. Terms, conditions, and rates are subject to change without notice. The information provided is for dissemination to and for the use of real estate and financial entities only and is not an advertisement for the extension of credit to consumers.

The advertiser paid a fee to promote this sponsor article and may have influenced or authored the content. The views expressed in this article are those of the advertiser and do not necessarily reflect those of this site or affiliated companies.

GET MORE INFORMATION